
When severe weather strikes St. Cloud, Sartell, Waite Park, Sauk Rapids, Cold Spring, or the Brainerd Lakes Area, filing a roof insurance claim requires exact line-item documentation and forensic proof. Insurance companies process claims using specialized software like Xactimate, making general cash estimates useless for securing full coverage.
Why Standard Estimates Fail
Insurance adjusters evaluate claims based on specific line items, regional labor rates, and mandatory building codes. Cash quotes often miss necessary requirements, such as Minnesota building code mandates for ice and water shield underlayment extending 24 inches inside the warm wall line. Submitting a basic cash estimate leads to missing line items and lower payouts.
The Inspection Process
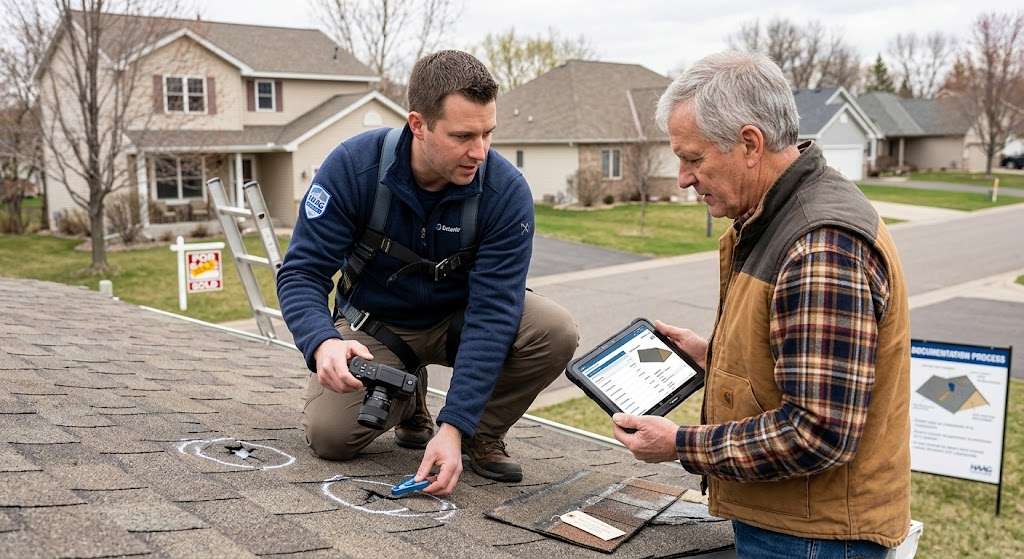
Identifying hail damage requires looking beyond surface granule loss. High-velocity hailstones fracture the underlying fiberglass mat inside asphalt shingles. Over time, freeze-thaw cycles expand these hidden tears, leading to active leaks and rotted roof sheathing.
Working with a HAAG Certified Residential Inspector, such as Exterior Pro co-owner Josh Helberg (HCI No. 200804118), ensures damage is evaluated using industry standards. This level of inspection prevents insurance adjusters from categorizing functional hail impacts as ordinary wear and tear.
Material Matching Laws and Laboratory Testing
When a storm damages part of a roof, insurance companies may try to approve a partial patch. If the installed shingle line is discontinued or faded by UV exposure, patching creates an uneven look.
Minnesota law requires insurance coverage to restore a home to a uniform appearance. When material availability is uncertain, a shingle sample is removed, properly sealed, and submitted to ITEL Laboratories. ITEL performs microscopic analysis to determine if the product is obsolete. An official ITEL report proving discontinuation requires the insurance carrier to approve a full roof replacement instead of a partial patch.
Full Building Envelope Coverage
Wind-driven hail hits more than just shingles. A proper evaluation covers the entire home exterior:
- Siding installation and trim for cracks in vinyl or chips in engineered wood
- Window wraps and frames for dented aluminum cladding and broken thermal seals
- Seamless gutters for granule accumulation that causes water to back up
Homeowners should avoid signing an Assignment of Benefits agreement that gives away insurance rights. Reputable local contractors work as construction advocates, meeting adjusters on-site without forcing homeowners to give up control of their policies.
Contact Exterior Pro
For questions about storm damage or active insurance claims, contact Exterior Pro for a detailed, photo-documented evaluation.
- St. Cloud Office: (320) 406-9427
- Direct Office Line: 844-ASK-4PRO
- Schedule directly: Free Storm Damage Inspection
Serving homeowners across the St. Cloud Location, Brainerd Lakes Area, and Little Falls Location.